

Weekly Market Review - 28 September 2026
Updated: Sep 29
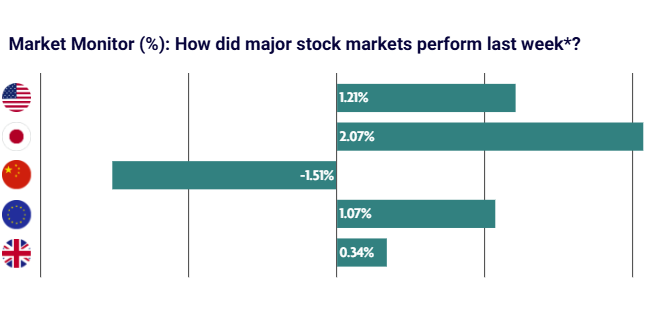
Global equities finished the week broadly higher led by the technology sector, as investors became increasingly bullish around the rise of agentic AI and the positive implications for overall AI demand. Japanese equities the standout, while Chinese equities lagged.
US: S&P GLOBAL COMPOSITE PMI DATA SUGGESTS ANNUALISED ECONOMIC GROWTH OF APPROXIMATELY 4% IN Q3
U.S. equities moved higher over the week, with the S&P 500 gaining 1.2%, driven largely by strength in technology and communication services stocks. Investor enthusiasm centred on Meta's strong consumer AI adoption and the potential impact of agentic AI on future computing infrastructure demand. Growth stocks outperformed value, while utilities and energy lagged amid concerns about higher interest rates. Economic data remained strong, with the September S&P Global Composite PMI rising to a 62-month high of 58.4, suggesting annualised economic growth of around 4% in the third quarter.
Both manufacturing and services activity accelerated, supported by robust new orders and production growth. However, stronger economic momentum and rising input costs fuelled concerns that inflation may remain elevated. Treasury yields surged following weak demand at several government bond auctions, with 10-year yields briefly exceeding 5.2% and 30-year yields rising above 5.5%, pressuring bond markets. Labour market data remained resilient, with jobless claims coming in below expectations and reinforcing the view that the economy continues to show notable strength.
JAPAN: TECHNOLOGY AND AI-RELATED STOCKS LEAD JAPANESE EQUITIES HIGHER
Japanese equities advanced during a shortened trading week, with the Nikkei 225 gaining just over 2%. Technology and semiconductor stocks led gains as investors reacted to the strong performance of U.S. AI related shares during Japan's market holiday period. Gains broadened later in the week to include banks, which benefited from rising bond yields and improved earnings expectations. Japanese government bond yields moved higher, largely tracking the sell-off in U.S. Treasuries and reflecting ongoing inflation concerns.
The Bank of Japan's recent interest rate increase was viewed as less hawkish than expected, although Governor Ueda maintained a tightening bias by highlighting upside inflation risks. Meanwhile, the yen weakened before recovering, with investors remaining alert for potential government intervention to support the currency.
CHINA: CHINA-US TRADE TRUCE EXTENDED UNTIL JANUARY 2027
Chinese equities declined over the week, with mainland growth stocks and Hong Kong technology shares among the weakest performers. Markets initially traded higher but later reversed as persistently high U.S. bond yields, elevated oil prices and weaker sentiment towards growth sectors weighed on investor confidence. Technology, AI, gaming and electric vehicle related stocks were among the main laggards. Investor optimism also faded as expectations for significant progress in U.S.-China negotiations diminished. However, the two countries agreed to extend their existing trade truce until January 2027, providing some stability while discussions continue. Despite the extension, markets remained cautious as investors assessed the outlook for growth, trade relations and global monetary policy.
EUROPE: EUROZONE BUSINESS ACTIVITY STRENGTHENS MORE THAN EXPECTED
European equities finished modestly higher, despite ongoing concerns around inflation and interest rates. Germany’s DAX closed 0.41% higher, France’s CAC 40 Index rose 0.16%, and Italy’s FTSE MIB gained 0.62%. Markets were supported by signs that economic growth across the eurozone continues to improve. Flash PMI data showed eurozone business activity strengthening more than expected, with both manufacturing and services contributing to growth.
Germany's business confidence also improved for a fifth consecutive month, reaching its highest level since May 2023. At the same time, rising input costs and selling prices highlighted that inflationary pressures remain persistent. Investors balanced optimism around growth and AI related themes against the risk that stronger data could prompt further ECB policy tightening.
UK: ECONOMIC DATA SUGGESTS SLOWING ECONOMIC GROWTH & RENEWED INFLATIONARY PRESSURES
UK equities rose modestly over the week, with the FTSE 100 gaining 0.3%. Economic data pointed to softer underlying activity, however, with retail sales sentiment deteriorating further and supplier orders falling at the fastest pace since records began. Flash PMI data showed overall business activity slowing, with the composite reading easing to 51.7 from 52.5. The slowdown was driven mainly by weaker services sector growth. Manufacturing proved more resilient, with activity continuing to expand. Input cost inflation accelerated, partly due to higher fuel prices, creating a challenging backdrop of slower growth alongside renewed inflation pressures.

What’s Important Next: 28 September to 2 October 2026
October’s release of PMIs and US Payrolls
On Thursday we get September’s Purchasing Manager Index (PMI) data and on Friday the latest US payroll figures are released.
Why it’s important
PMI data is one of the best forward-looking indicators of business activity. Thursday’s releases cover Asia, Europe, the UK and the US.
Over the last few months, investors have been focused on the outlook for interest rates, with markets pricing in the possibility that borrowing costs could remain higher for longer. Higher rates affect everything from mortgages and business loans to the cost of government borrowing. When rising rates are driven more by inflation concerns than economic growth, the impact on investor sentiment and asset prices is typically negative. Any signs that higher borrowing costs are beginning to slow economic activity or dampen consumer and business confidence will therefore be closely watched.
The US non-farm payroll report will provide further clues on the health of the world’s largest economy. Last month’s data was surprisingly strong, pointing to a resilient economy and increasing expectations of further interest rate rises. Investors will be looking to see whether that strength has been maintained, or whether higher rates are starting to have an effect.
UK Labour Party conference
The UK Labour Party conference begins over the weekend, with Prime Minister Andy Burnham due to address delegates on Tuesday.
Why it’s important
"Labour policy? What policy?"
While some may view that criticism as harsh, there is a degree of truth in it. Despite being Prime Minister for more than two months, Burnham has largely kept his cards close to his chest when it comes to economic policy and taxation.
The conference provides an ideal platform for the government to outline more concrete policy proposals and potentially test the waters on tax measures ahead of the Autumn Budget on 28 October.
Investors, businesses and the Bank of England will be listening closely. Any indication of how the government intends to manage growth, borrowing and public spending could have implications for both gilt and equity markets. While Burnham will undoubtedly be pleased to have successfully navigated his first meeting with President Trump, investors will now be looking for signs of domestic leadership and a clearer sense of direction on economic policy.
This update reflects our view at the time of writing and is subject to change. The document is for informational purposes only and is not investment advice. Omnis Investments is unable to provide investment advice. Every effort is made to ensure the accuracy of the information, but no assurance or warranties are given. Past performance should not be considered as a guide to future performance.


Comments